How to Plan for Annual Bills and Irregular Expenses
Annual bills derail pay cycles because they're forgotten, not because they're unexpected. Learn to list, map, and save for irregular expenses so the money is there when the bill arrives.

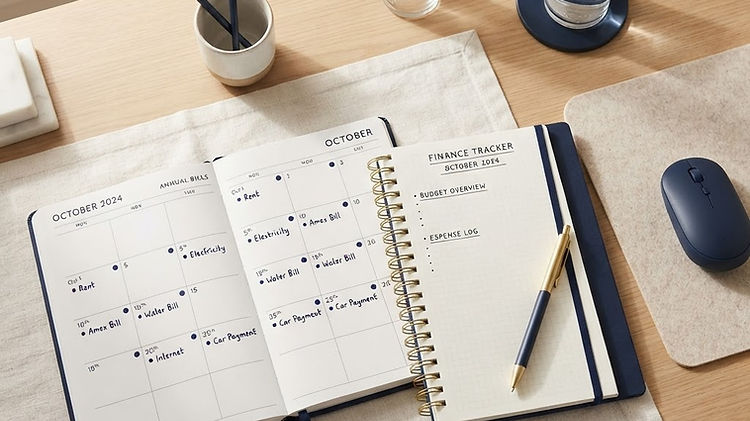
The problem with annual bills
Annual and irregular bills are the expenses that most often derail a pay cycle. They don't happen every pay, so you forget about them — and then they arrive all at once, and you're scrambling.
The common ones:
- Car registration
- Car and home insurance renewals
- Council rates
- Professional memberships and licences
- Health insurance (if paid annually)
- School fees and costs
- Christmas and holiday spending
- Back-to-school costs
- Annual subscriptions (software, gym, car associations)
If two or three of these arrive in the same month, it can wipe out a pay cycle — or worse, push you into debt. The solution is planning for them before they arrive.
Step 1: List every irregular expense
Start by listing every expense that doesn't happen weekly or monthly but that you know is coming. Go through your bank statements for the past 12 months and look for:
- Annual payments — anything charged once a year
- Quarterly payments — utilities, some insurance, body corporate fees
- Half-yearly payments — some insurance, some subscriptions
- Seasonal expenses — Christmas, school costs, holiday spending
For each one, note:
- What it is
- How much it costs (use last year's amount, add 5–10% for increases)
- When it's due (month, or specific date if you know it)
Step 2: Map the timing
Once you have the list, map when each expense falls across the year. You'll quickly see whether they're spread out or clustered:
| Month | Expense | Amount | |---|---|---| | January | School fees | $400 | | March | Car rego | $600 | | April | Home insurance | $1,200 | | June | Car insurance | $800 | | September | Council rates | $900 | | December | Christmas | $800 | | Total | | $4,700 |
If several fall in the same month, that's your danger period. You need to have enough saved by then to cover them all.
Step 3: Calculate the per-pay contribution
Add up the total annual cost of all irregular expenses, then divide by the number of pay cycles per year:
- Fortnightly pay: divide by 26
- Weekly pay: divide by 52
- Monthly pay: divide by 12
For $4,700 of annual irregular expenses on a fortnightly cycle:
$4,700 ÷ 26 = $181 per fortnight
This is the amount you need to set aside each pay so that when each bill arrives, the money is already there. It's the core of a sinking fund approach.
Step 4: Set up the system
Where to put the money
- A separate savings account — the simplest approach. Move the per-pay contribution there every payday and track the total against your list.
- Multiple accounts — one per category. Clearer, but more accounts to manage.
- An offset account — if you have a mortgage, parking the sinking fund in your offset saves interest and the money is still accessible.
How to track
If you're using one account for multiple expenses, track the balance per category in a spreadsheet:
| Category | Annual cost | Saved so far | Due | Ready? | |---|---|---|---|---| | Car rego | $600 | $550 | March | 92% | | Home insurance | $1,200 | $1,100 | April | 92% | | Christmas | $800 | $730 | December | 91% |
When a bill arrives, check the spreadsheet, pay it from the sinking fund, and reduce that category's balance.
Make it automatic
Set up an automatic transfer from your everyday account to the sinking fund account on payday. The amount is the total per-pay contribution from Step 3. If the money moves automatically, you don't have to think about it — and you can't spend it on something else.
Step 5: Handle the danger months
If several large bills cluster in one month, you need a larger balance built up before that month arrives. Two approaches:
Front-load the savings
If you know March has $1,800 of bills and you're starting in November, you have 4 months to save $1,800 — $450/month instead of the average $392/month. Save more early, then return to the normal rate.
Use a buffer
Keep a one-month buffer in the sinking fund account so that even if a cluster arrives, you can cover it. This is especially useful in the first year before the fund has had time to build up.
Step 6: Review annually
Once a year, review your irregular expense plan:
- Update the costs — insurance, rego, and rates increase. Add 5–10% to last year's figures.
- Add new expenses — a new subscription, a child starting school, a new insurance.
- Remove old ones — expenses you no longer have.
- Check the timing — if a renewal date has changed, update your map.
Common mistakes
- Using last year's exact cost. Costs go up. If your sinking fund is based on last year's insurance premium and it's increased 15%, you'll be short. Always add a buffer.
- Forgetting the smaller expenses. A $50 annual subscription is easy to miss, but if you miss several, they add up. Go through your statements systematically.
- Not starting early enough. If you start your sinking fund in November and Christmas is in December, you've only saved one month's contribution. Start in January for next December.
- Dipping in for other things. The sinking fund is for its specific expenses. If you raid it for a different purpose, the bill it was meant to cover will arrive and the money won't be there.
How Payday Compass helps
The Payday Compass app lets you set up a savings goal for each irregular expense category, track the progress, and see the per-pay contribution needed to stay on track. It also connects your sinking funds to your overall money runway, so you can see whether your irregular expense savings are affecting your day-to-day buffer.
For a quick check on whether the per-pay contribution fits your current cash flow, use the free payday calculator.
Summary
Annual and irregular bills derail pay cycles because they're forgotten, not because they're unexpected. The fix is to list every irregular expense, map when they fall, calculate the per-pay contribution, set up a separate account, and automate the transfer. When each bill arrives, the money is already there — no stress, no scrambling, no debt. Start with the biggest two or three expenses, and add more as the system proves itself.
Put it into practice
The Payday Compass workbook brings these ideas together in one organised spreadsheet.
Explore the Budget Planner


